21 Major Banks Are Joining Forces to Launch a Dollar Stablecoin
Wall Street is no longer just watching the stablecoin market from the sidelines.
It is preparing to build one.
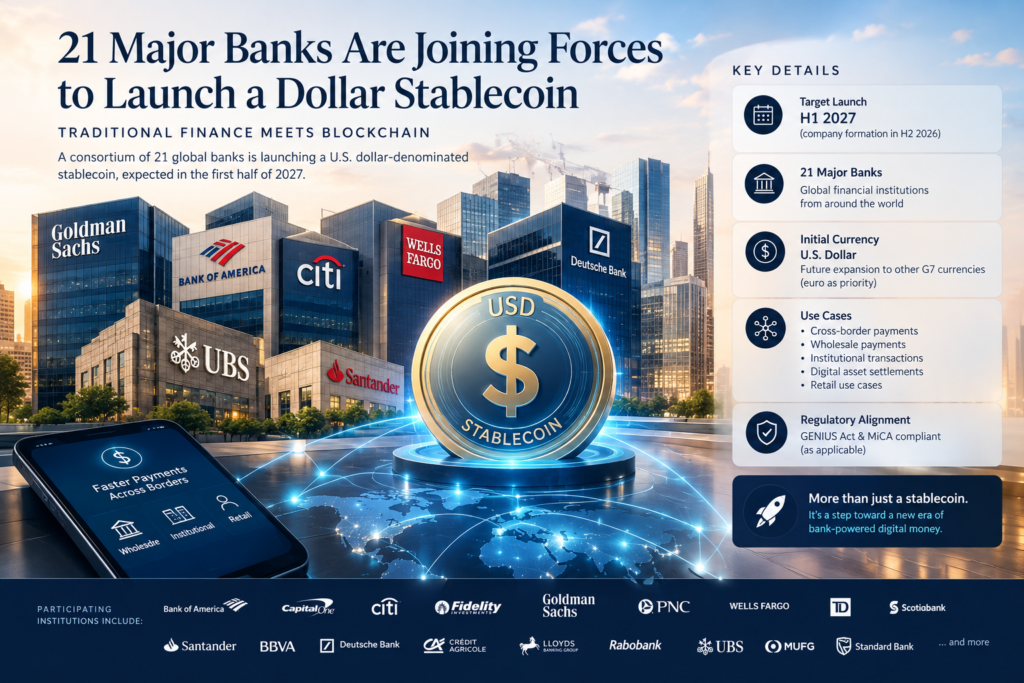
A group of 21 major financial institutions has committed to establishing a new company that could issue a U.S. dollar-denominated stablecoin, with the product targeted for launch in the first half of 2027.
The group includes some of the biggest names in global finance, including Goldman Sachs, Bank of America, Citi, Deutsche Bank, Wells Fargo, Fidelity Investments, UBS, Santander, and Standard Bank.
The company itself is expected to be established during the second half of 2026, subject to closing conditions.
And while the stablecoin does not exist yet, the announcement sends a much bigger message:
Traditional banks are becoming increasingly serious about blockchain-based money.
Who Is Behind the Stablecoin?
The initiative brings together financial institutions from several regions.
Among the participants are:
- Bank of America
- Capital One
- Citi
- Fidelity Investments
- Goldman Sachs
- PNC Financial Services
- Wells Fargo
- TD Bank Group
- Scotiabank
- Banco Santander
- BBVA
- Deutsche Bank
- Commerzbank
- Crédit Agricole
- Lloyds Banking Group
- Rabobank
- UBS
- MUFG Bank
- Standard Bank
- WisdomTree
- Sirius International Holding
The group was originally announced in October 2025 with only 10 banks exploring the idea.
It has now grown to 21 institutions.
That expansion may be one of the most important parts of the story.
This is no longer a small experiment involving a handful of banks.
It is becoming a coordinated institutional project.
What Are the Banks Actually Building?
The planned company intends to focus initially on a U.S. dollar-denominated stablecoin.
The longer-term plan could go even further.
The group says it wants to expand into stablecoins denominated in additional G7 currencies, with the euro identified as a priority.
The stablecoin is also expected to support multiple types of financial activity, including:
- Cross-border payments
- Wholesale payments
- Institutional transactions
- Digital asset settlements
- Retail use cases where digital money can provide benefits
In other words, the idea is not simply to create another cryptocurrency for trading.
The banks are looking at stablecoins as a potential piece of financial infrastructure.
Why Are Banks Suddenly So Interested in Stablecoins?
The answer is relatively simple.
Money is moving onto the internet.
Traditional banking systems are extremely important, but cross-border payments can still involve multiple intermediaries, different banking systems and settlement processes that are not always instantaneous.
Stablecoins offer another model.
A dollar stablecoin can represent digital money that moves across blockchain networks, potentially allowing transactions to happen around the clock and across borders.
For banks, that creates an interesting opportunity.
Instead of blockchain being something that exists outside the traditional financial system, banks can potentially use the technology themselves.
And that is exactly where the industry appears to be heading.
Regulation Has Changed the Conversation
The timing is also important.
The United States has been building a clearer regulatory framework for payment stablecoins.
The GENIUS Act, signed into law in July 2025, established a federal framework for permitted payment stablecoin issuers.
In August 2026, the U.S. Treasury also released proposed rules for implementing parts of the law.
The expected effective date for the GENIUS Act is January 18, 2027, subject to the conditions laid out in the legislation and implementing rules.
That timeline lines up closely with the banks’ own plans.
For financial institutions, regulatory clarity can make it easier to move from experimentation to actual product development.
The 21-institution group says its initiative intends to be GENIUS Act and MiCA compliant, as applicable.
That does not mean the project has already received every approval it needs.
But it shows how closely the stablecoin project is being designed around the emerging regulatory environment.
Is This a Threat to Tether and Circle?
Potentially.
The stablecoin market is currently dominated by crypto-native companies.
Tether’s USDT remains the largest dollar stablecoin by circulation, while Circle’s USDC has become one of the most widely used regulated dollar-backed digital currencies.
For years, these companies have effectively occupied the stablecoin market while traditional banks watched from a distance.
Now the situation is changing.
A stablecoin backed by a consortium of major financial institutions would bring something that crypto-native issuers cannot easily replicate:
existing banking relationships.
These institutions already have corporate clients, payment networks, compliance teams, liquidity infrastructure and relationships with regulators.
That could give a bank-backed stablecoin a very different starting point.
But Bigger Does Not Automatically Mean Better
There is an important reality check here.
A large group of banks launching a stablecoin does not guarantee that customers will actually use it.
The market already has established products with significant liquidity and network effects.
And there is evidence that simply putting a bank’s name behind a stablecoin does not automatically create demand.
Societe Generale, for example, became one of the first major banks to launch a dollar-backed stablecoin through its digital asset subsidiary.
Yet its token has seen relatively limited circulation compared with the dominant stablecoins.
That raises a crucial question for the 21-bank consortium:
Can traditional finance build a stablecoin that people actually want to use?
The Real Competition May Be Infrastructure
The biggest story may not be about replacing USDT or USDC.
It could be about changing the infrastructure underneath global payments.
Imagine a multinational company moving money between subsidiaries in different countries.
Instead of relying entirely on conventional correspondent banking channels, some parts of the process could eventually happen using regulated stablecoins.
The same infrastructure could potentially support digital asset settlement, treasury operations and other institutional transactions.
That is why the consortium’s focus on wholesale and institutional use cases matters.
The banks may not be trying to turn everyone into a crypto trader.
They may be trying to make blockchain-based settlement part of normal financial operations.
Why the 21-Bank Structure Matters
There is another interesting element to the project.
The stablecoin is not being developed by a single bank.
It is being built by a group of financial institutions spread across North America, Europe, Asia, the Middle East and Africa.
That gives the initiative a potentially global distribution network from day one.
It also reflects something that has been happening across financial markets:
competition and cooperation are happening at the same time.
These banks compete with each other for customers, payments and financial services.
Yet they also share an interest in building infrastructure that can work across institutions.
Stablecoins could become one of those areas where cooperation makes economic sense.
And the Banks Are Not Stopping at the Dollar
The initial focus is clearly the U.S. dollar.
But the longer-term ambition is broader.
The consortium says it intends to expand into other G7 currencies, with the euro as the priority.
That could eventually create a network of institution-backed stablecoins covering multiple major currencies.
If that happens, stablecoins could become more than dollar tokens used mainly within crypto markets.
They could become a digital representation of major currencies used across global financial systems.
That would be a much bigger development.
There Is Already Competition Among Banks
The 21-bank project is not the only sign that traditional financial institutions are moving into stablecoins.
Another consortium of 37 financial institutions has formed a company called Qivalis and plans to launch a euro-pegged stablecoin.
Some institutions, including BBVA, are involved in both initiatives.
That means banks are not simply experimenting with stablecoins individually.
They are increasingly forming alliances around shared digital-money infrastructure.
The competition may eventually become less about whether banks will use stablecoins and more about which stablecoin networks become widely adopted.
What Does This Mean for Crypto?
For the crypto industry, this could be a major validation.
Stablecoins have spent years being treated as one of crypto’s most useful real-world applications.
Now some of the world’s largest financial institutions are reaching a similar conclusion.
The difference is that banks are approaching stablecoins from a different direction.
Crypto companies built stablecoins first and expanded toward traditional finance.
Banks are now building their own digital-money infrastructure while bringing traditional finance with them.
The two worlds are beginning to overlap.
What Could Change by 2027?
If the project reaches its planned launch, 2027 could become an important year for institutional stablecoins.
Banks could begin offering digital dollar infrastructure directly to customers.
Financial institutions could use stablecoins for settlement.
Cross-border payments could become more programmable.
Digital assets could become more closely connected to traditional banking.
And competition between bank-issued stablecoins and existing crypto-native products could become much more intense.
But there are still several steps between today’s announcement and a live product.
The company has to be established.
The technology has to be built.
Regulatory requirements have to be met.
And, perhaps most importantly, customers have to actually use the stablecoin.
The Bigger Picture
The most interesting part of this story is not simply that 21 banks want to launch a stablecoin.
It is what that decision says about the direction of finance.
For years, blockchain was often presented as an alternative to traditional financial institutions.
Now some of those same institutions are actively exploring blockchain as part of their own infrastructure.
Goldman Sachs, Bank of America, Citi, Deutsche Bank and their partners are not entering crypto because the technology suddenly became fashionable.
They are responding to a financial system that is gradually becoming more digital, more programmable and more connected to blockchain networks.
The stablecoin planned for 2027 may or may not become a major competitor to USDT or USDC.
But the decision by 21 major institutions to build it is already significant.
Wall Street is no longer asking whether stablecoins belong in finance.
It is starting to ask how much of finance they could eventually power.
Need to Receive International Payments?
Open your USD, GBP & EUR account with Kolan.
Fill out the form and book your free consultation.
Open Your Account: https://bit.ly/4iYqi4N
Shop OneKey
Looking for secure crypto hardware to protect your digital assets?
Shop OneKey: https://onekey.so/r/TRC
Join Our Community & Let’s Discuss
Want to stay updated on crypto, blockchain, DeFi, RWA, payments, regulation, and the latest market developments?
👥 WA Community: https://chat.whatsapp.com/BfQJOFveLuK8QShcJnxDJF
🌐 Telegram Group: https://t.me/cryptomartlive
📲 Telegram: @sungazerlive
📸 Instagram: @cryptomartlive
Crypto moves fast. Stay informed. Stay ahead.
Tinggalkan Balasan